Editors Picks

Quirkyjournals.com — Our Editor’s Picks — Curated selections of the best tools, gadgets, luxury items, and marketing essentials chosen by our team. Explore our top recommendations and discover what’s worth your attention.

Beyond the Bottom Line Why Purpose-Driven Finance is Essential for Society

Purpose-Driven Finance: ESG, Impact and Real Change

Beyond the Bottom Line: Why Purpose-Driven Finance is Essential for Society
A comprehensive examination of how purpose-led financial institutions, ESG integration, impact investing, and values-aligned financial planning are reshaping capital markets and why the shift is not just ethical, but economically necessary.
Finance Has Always Had Power. The Question Is What It Does With It.
Every mortgage signed, every investment made, every loan extended or denied is a small act of world-shaping. Financial institutions direct trillions of dollars each year toward specific uses, specific industries, and specific people. Collectively, these decisions determine which businesses receive the capital to grow, which communities gain access to opportunity, and which environmental futures are funded into existence.
For most of the modern era, this power operated under a single governing principle: maximise financial return. Profit was the purpose. Everything else, social impact, environmental consequence, and community effect, was either an externality to be managed or an irrelevance to be ignored. The doctrine of shareholder primacy, articulated most influentially by economist Milton Friedman in 1970, provided the intellectual architecture: the social responsibility of business is to increase its profits.
That architecture is cracking. Not because profits no longer matter, they do, and purpose-driven finance does not dispute this, but because decades of purely profit-driven capital allocation have produced costs that are becoming increasingly impossible to ignore. Climate change is fuelled in part by capital directed toward fossil fuel expansion over renewable alternatives. Systemic inequality, reinforced by financial systems that excluded the already-marginalised while enriching the already-wealthy. Institutional distrust as financial crises revealed the gap between what banks said they stood for and what they actually did with other people’s money.
Purpose-driven finance is the emerging answer to this accumulated reckoning. It encompasses individual financial planning aligned with personal values, institutional investment strategies that integrate environmental and social factors alongside financial returns, and an entirely new category of financial institutions whose governing model places social and environmental impact alongside, not above, financial performance.
As Harvard Business School Online’s analysis of purpose-driven firms observes, some of the most successful companies now focus beyond profit margins and returns on investment to craft strong mission statements and purpose-driven strategies. The question driving this article is not whether purpose-driven finance is a nice idea. It is why it is an essential one for society, for institutions, and ultimately for the financial system’s own long-term sustainability.
Defining Purpose-Driven Finance: More Than a Marketing Claim
Purpose-driven finance is a term that has attracted both genuine practitioners and cynical opportunists. ‘Greenwashing’, the practice of marketing financial products as sustainable or ethical without substantive changes to underlying behaviour, is a genuine and pervasive problem. Consequently, a precise definition matters enormously. It separates transformative practice from performative branding.
At its core, purpose-driven finance has th

Purpose-Driven Finance: ESG, Impact and Real Change Read More »
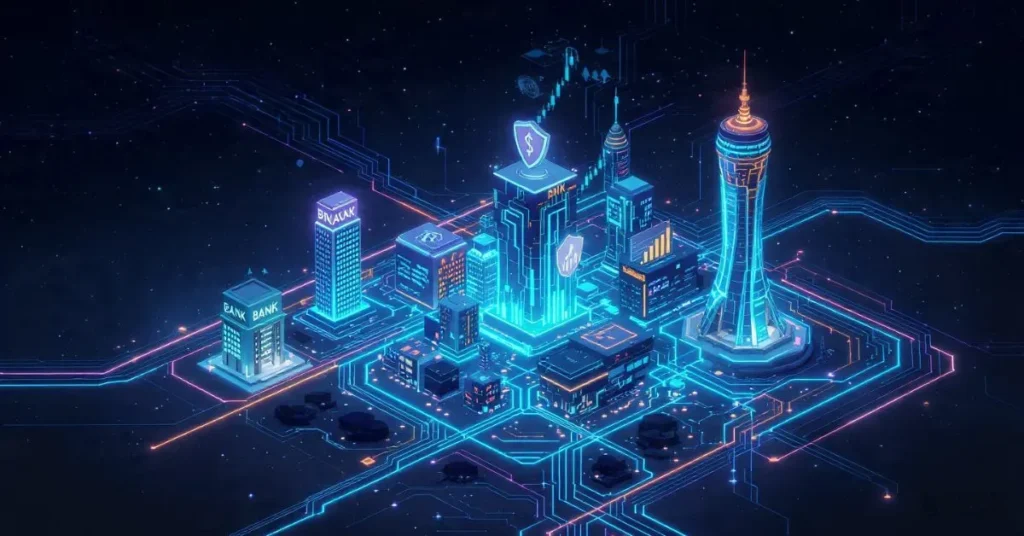
Components of the Financial Services Sector and AI Integration Between Them

Financial Services Components and How AI Connects Them

For most of the last century, banks, insurers, asset managers, payment networks, and capital markets firms ran on separate technology stacks, guarded their own data, and optimised for narrow regulatory mandates. AI is dismantling that architecture. Machine learning models trained on payments data now inform credit decisions, insurance pricing borrows techniques from hedge fund risk engines, and conversational AI front-ends sit on top of everything from current accounts to brokerage and lending. Research shows AI in finance has evolved from simple rules-based automation into predictive, decision-support infrastructure that cuts across traditional subsectors, forcing incumbents to rethink where one “business line” ends and another begins.

Financial Services Components and How AI Connects Them Read More »

The Hidden Danger Why Low-Limit Credit Cards Can Wreck Your Credit Score 

Low-Limit Credit Cards: The Hidden Credit Score Trap

A $500 store card feels harmless until you swipe it a few times. Put just $200 on a $500 limit and your utilisation jumps to 40%, signalling risk to lenders even if you pay on time. Because credit scores heavily weight how much of your available credit you appear to be using, low-limit cards can function like score traps — keeping you in a high-utilisation zone that raises borrowing costs and undermines long-term wealth-building unless you manage them with surgical precision.

Low-Limit Credit Cards: The Hidden Credit Score Trap Read More »

Finance Genius or Financial Mess 15 Signs You Need to Call for Help

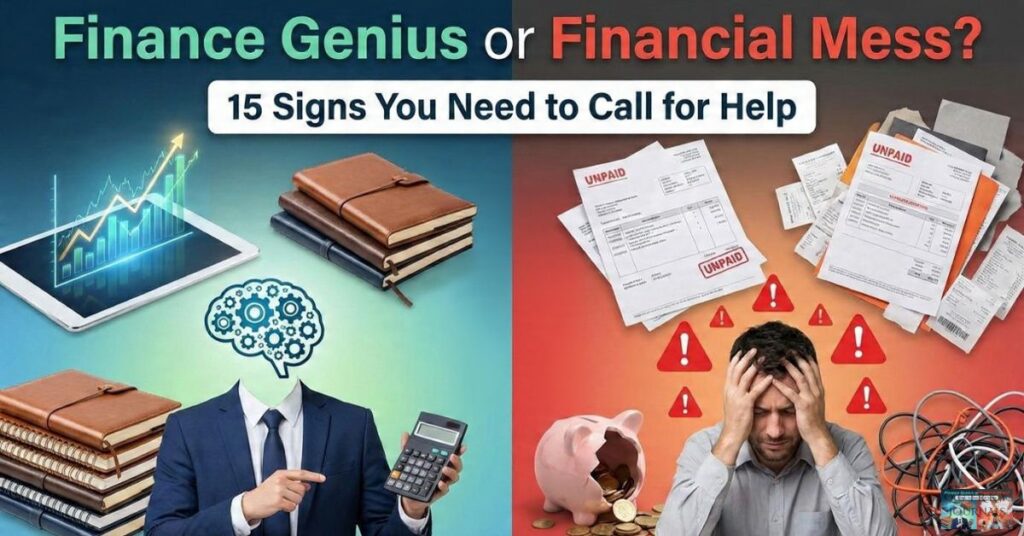
How to Tell If You’re a Finance Genius—or Quietly Headed for Trouble

Most people are sure they’re “okay” with money—until a job loss, rate hike, or medical bill exposes how fragile their finances really are. True financial competence isn’t about your income level or job title; it’s about how you make decisions, manage risk, and respond under pressure. This guide lays out clear signs you’re financially on top of things—detailed tracking, real understanding of concepts like compound interest and risk‑adjusted returns, strategic planning—and equally clear warning signs that you’re in over your head and should bring in a professional before small problems turn into full‑blown crises.

How to Tell If You’re a Finance Genius—or Quietly Headed for Trouble Read More »

Should You Save or Invest First? Best Strategy for Beginners

Should You Save or Invest First? Best Strategy for Beginners

Skip investing until you have $1K starter emergency fund + no credit card debt—20% APR debt kills 8% stock returns. After: max 401(k) match (free 100% return), Roth IRA, then taxable brokerage. Use 3-fund portfolio (US stock + international + bonds). DCA monthly to avoid timing mistakes. Early career: 80-90% stocks.

Should You Save or Invest First? Best Strategy for Beginners Read More »

Whole Life Insurance Audit An Objective Review of Cash Value vs. Term Yields

Whole Life Insurance Audit: An Objective Review of Cash Value vs. Term Yields

Whole life insurance promises lifetime coverage, steady cash value growth, and potential dividends — but those guarantees come with high premiums, steep early surrender charges, and often lower long‑term returns than simply buying term and investing the difference. This audit breaks down how cash value is built, what “guaranteed” growth actually means after fees, how participating dividends really work, and how whole life policies stack up against term life using research from consumer advocates, insurers, and peer‑reviewed studies.

Whole Life Insurance Audit: An Objective Review of Cash Value vs. Term Yields Read More »

Pricing Psychology How Tiny Price Changes Dramatically Shift Demand

Pricing Psychology: How Tiny Price Changes Dramatically Shift Demand

Shifting a price from 10.00 to 9.99 can raise sales by up to 24 because buyers react to the leftmost digit, not the one‑cent difference. This guide breaks down charm pricing, psychological price thresholds, anchors, decoys, dynamic pricing risk, and subscription psychology, then shows you how to A/B test these tactics so you can improve unit economics without eroding trust or perceived value.

Pricing Psychology: How Tiny Price Changes Dramatically Shift Demand Read More »

The AI Startup Graveyard Why 80% Fail and How 20% Beat the Odds

The AI Startup Graveyard: Why 80% Fail and How 20% Beat the Odds

The AI boom hides a brutal reality: 80% of AI projects fail, 95% of GenAI pilots never deliver financial results, and by 2026 at least 30% of GenAI initiatives will be abandoned after proof‑of‑concept. ContentGenius (an OpenAI wrapper) died when API pricing and churn destroyed its economics, MediPredict’s hospital ML failed on messy, fragmented data and HIPAA friction, and RetailOptimize proved that “accurate” forecasts are worthless if they don’t tie to KPIs or workflows. The pattern is clear—teams start with shiny models instead of real business pain, underestimate data and infrastructure, and chase impossible problems—so this guide lays out concrete moats (proprietary data, deep integrations, domain focus), a 60–70% data‑infrastructure allocation rule, and a 3‑stage checklist founders can use to keep their AI startup out of the graveyard.

The AI Startup Graveyard: Why 80% Fail and How 20% Beat the Odds Read More »